Editor’s Note: Overdraft Apps provides detailed product reviews and recommendations based upon extensive research and our own hands-on testing. We may earn a referral fee when you sign up for or purchase products mentioned in this article.
Updated September 2026.
If you are hunting for the best cash advance, start with apps you already use to manage money. Five popular ones hide an advance inside the same account where your paycheck lands. Number five is not even a bank. It is the app a lot of people already use to split a dinner bill, and for some users it quietly offers more cash than anything else on this list.
Standalone products like Brigit or Dave exist only to lend and collect a fee or subscription. The five below bake the advance into everyday banking (or banking-like) tools. That can mean lower fees, longer repayment, or a higher ceiling, but it also means your next deposit often pays the advance back before you can touch the money.
Watch the walkthrough, then use the table and sections below for the fee and limit details.
| App / product | Typical max | What it costs | Repayment |
|---|---|---|---|
| Varo Advance | Up to $500 | Flat fee (varies with deposits; no subscription) | Up to 30 days |
| Current Paycheck Advance | Up to $750 | Free in ~3 business days; Instant Access fee shown only in-app | Next payroll deposit |
| Chime MyPay | Up to $500 | Instant: 3% ($2 min, $5 max); free in ~24 hours | Next pay period |
| Upgrade Boost Cash | Up to $500 | Free plan: 3-5 business days; Premium $9.99/mo for instant | Up to 34 days |
| Cash App Borrow | Invite-only; often starts smaller | Flat 5%; late fees if you miss | Installments over about 4 weeks |
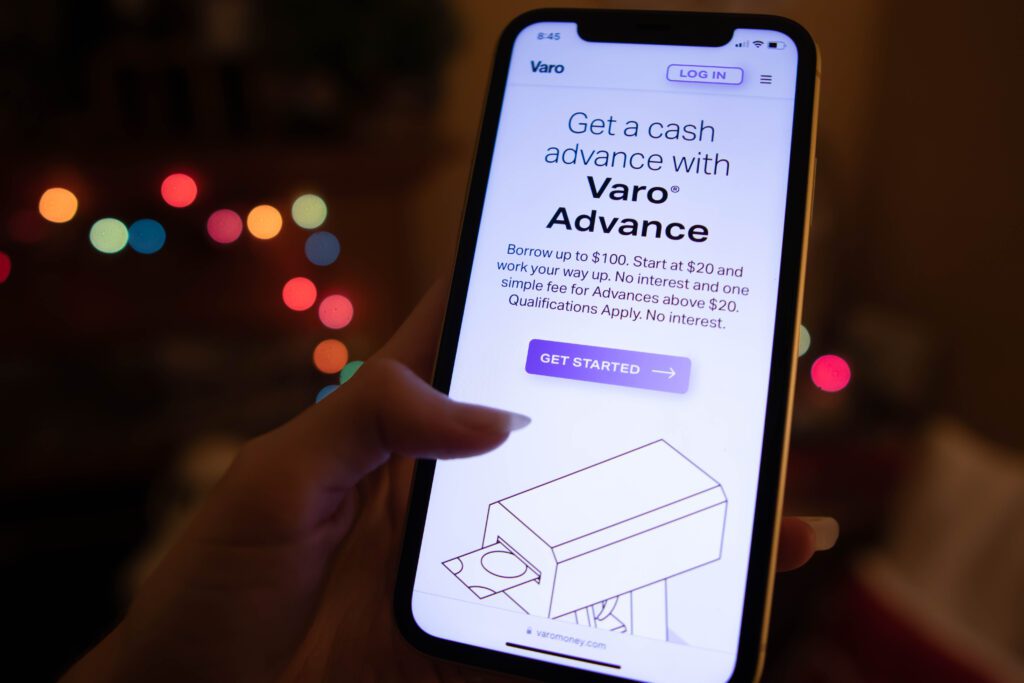
Varo Advance: Best flexible repayment
Varo is a mobile-only bank with checking, savings, and a debit card. Most everyday banking features are free. Varo Advance sits inside that account and can run from about $20 up to $500 for eligible customers.
There is no subscription. You pay a flat fee that depends on how much you bank with Varo. With roughly $800 or more in monthly deposits, a $100 advance is often about $8. Without that deposit history, fees climb fast. A $250 advance can land closer to $40.
Repayment is the main reason to check Varo first. You can get up to 30 days to pay it back. Even if you pick an earlier date and miss it, you still have that longer window. That is more breathing room than apps that auto-pull on your next payday.
The tradeoff: your advance and your paycheck sit in the same place. Varo prioritizes paying the advance from incoming deposits, so that money can come off the top before you spend it.
Current: Highest advertised ceiling
Current is a banking app with checking, savings, early paycheck options, and Paycheck Advance. Eligible members can see limits up to $750, the highest published max among these five if you set Cash App Borrow aside.
You need real payroll deposits. A common floor is at least one $200 payroll deposit per month, and bigger, steadier deposits unlock higher amounts. Venmo-style transfers do not count, so this is a weak fit for many gig workers.
There is no subscription. Repayment comes from your next payroll deposit into Current. Savings pods also pay a bonus rate if you park cash there, which can help you build a small cushion after the advance is gone.
What we do not like: Current does not publish its Instant Access fee on marketing pages. You only see the dollar amount inside the app when you request the advance. Standard delivery is free if you can wait about three business days. If you need money the same day, you are agreeing to a fee you cannot compare ahead of time.
Check Current’s advance limits
Chime MyPay: Cheapest fees by a wide margin
Chime is the most widely used banking app in this group. MyPay can spot eligible members up to $500. Instant delivery costs 3% of the advance, with a $2 minimum and a $5 maximum. A $100 advance is about $3 for instant. A full $500 advance tops out at $5. That is lower than every other option here.
If you can wait about 24 hours, delivery is free. There is no subscription, no tip prompt, and no interest. You do need a Chime account and qualifying direct deposits (often at least $200 a month to get in the door, and usually more for higher MyPay amounts). Many people start around $50 to $100 and build toward $500 over time.
Upgrade Boost Cash: Strong free plan, optional Premium
Upgrade is a major online lender. Boost Money is its banking-style product: spending and savings accounts, a card, early direct deposit for many payers, no overdraft fees on the spend account, and a large fee-free ATM network. Some debit activity can also report to credit bureaus, so the account can help build credit while you bank.
Boost Cash is the advance inside that product. Eligible users can borrow up to $500. There is no interest and no late fee on the advance itself. Repayment is tied to your paycheck, with up to 34 days to repay on terms shown in the app.
The free plan is usable: standard delivery takes 3 to 5 business days. Premium is $9.99 a month and unlocks instant delivery with no separate express fee, a faster path toward the full $500, and a higher savings yield. If you take advances often, Premium can cost less than stacking per-transfer express fees on other apps.
Read the Upgrade Boost Cash review
Cash App Borrow: The one most people miss

Cash App is not a traditional bank, but millions of people already have it for peer payments. Inside the Money tab is Cash App Borrow. You cannot apply. It has to appear on your account. Cash App does not publish a clear eligibility checklist. Consistent use and direct deposits around $500 a month or more seem to help, based on what users report.
Offers often start small, around $150 or less. Some users later report limits of $1,000, $2,000, or higher after months of activity. Treat those higher numbers as user reports, not a promised ceiling. There is no credit check. The fee is a flat 5% (about $5 per $100). You can hold more than one advance at a time, and repayment can run in installments over about four weeks.
The downside: late fees. Cash App Borrow can charge about $5 after a few days late, then about 1.25% weekly while it stays unpaid. Most of the banking-app advances above do not pile on weekly late charges like that.
Which one should you open first?
- Cheapest fees: Chime MyPay ($2 to $5 for instant, or free in a day)
- Highest published limit: Current at $750
- Most flexible repayment among the banks: Varo (up to 30 days)
- Best free-tier banking advance: Upgrade Boost Cash (3-5 day delivery, up to 34 days to repay)
- Highest reported ceiling if you already have access: Cash App Borrow
If your paycheck already hits one of these five, check that app before you download a new cash advance product. You may already qualify, and the fee can be far lower than a standalone app.
If you need money today and you are not set up with any of these accounts, use a standalone cash advance instead. We keep a roundup of apps built for same-day funding without an existing banking relationship: best cash advance apps.
Frequently asked questions
Which banking apps have a hidden loan feature?
Varo (Varo Advance), Current (Paycheck Advance), Chime (MyPay), Upgrade (Boost Cash), and Cash App (Borrow) all include a built-in cash advance. You use an app already on your phone instead of signing up for a separate advance-only product.
How do I find the cash advance in my banking app?
Open the app and look under Money, Move, Borrow, MyPay, Advance, or Boost Cash. These tools often sit a few menus deep, which is why people who already qualify never tap them.
How much does a hidden loan feature in a banking app cost?
Chime MyPay instant delivery is 3% with a $2 minimum and a $5 cap. Current is free if you wait about three business days (Instant Access pricing is only shown in-app). Varo uses a flat fee that rises or falls with your deposits. Upgrade’s free plan takes 3 to 5 business days; Premium is $9.99 a month for instant delivery. Cash App Borrow charges a flat 5%.
What happens if I do not repay a banking-app cash advance?
These products are not traditional installment loans. Many providers let you push a repayment date, and they generally do not use classic debt-collection lawsuits the way a credit card might. When you bank and borrow in the same app, though, repayment usually comes automatically from your next deposit, so the money leaves before you can spend it. Missing payments can also shrink or pause future advances.
Do these hidden advance features affect my credit score?
Most of these advances do not run a hard credit check or report the advance itself like a loan. Upgrade’s Boost Money can report some debit activity to help build credit. Always confirm the current terms in the app before you borrow.
What if none of these apps are already on my phone?
Standalone cash advance apps are built for one-time use without an existing banking relationship with that provider. See our cash advance apps roundup for same-day options.